Lovys

Landlord insurance (PNO)

Finally sleep soundly with our online landlord insurance, from just €5.80/month.
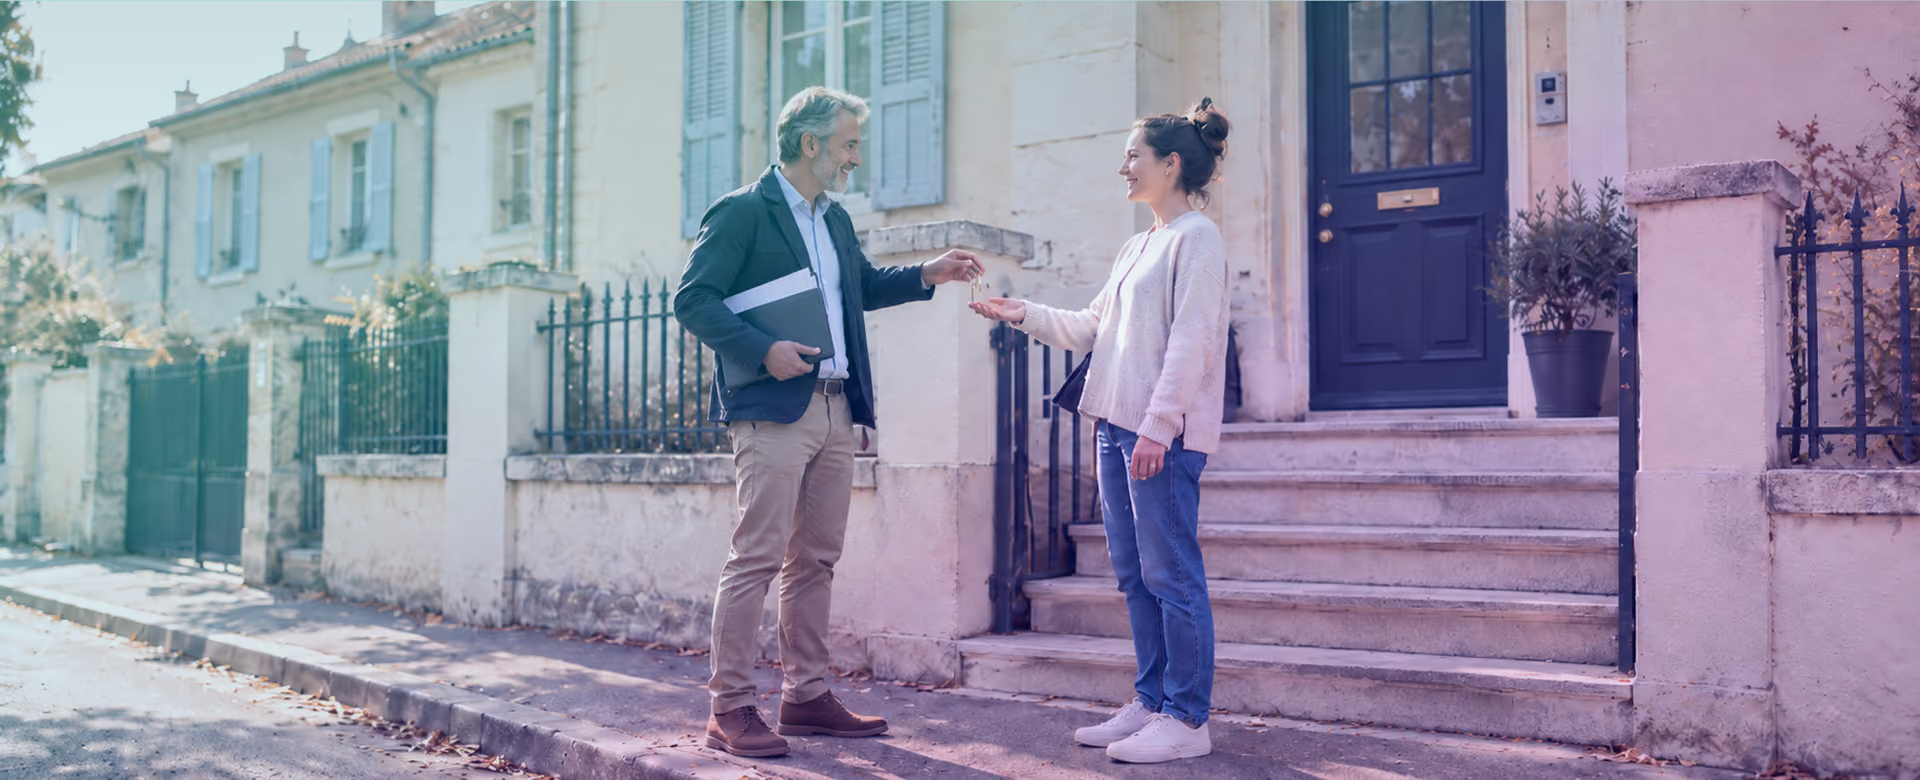
Landlord handing the keys to her tenant in front of a house, illustrating Lovys landlord insurance
Over 50,000
policyholders trust Lovys
Google logo
Google reviews
Rated 4 out of 5 stars
4.0 | 3,083
reviews
3D icon of a furnished living room, illustrating Lovys home insurance
Lovys

Why choose Lovys landlord insurance?

Although landlord insurance isn't compulsory, unlike tenant insurance, it will protect your property come rain or shine if you ever have to deal with a claim. Even if you don't live there!
‍
Tailor-made landlord insurance: we'll cover you in 2 minutes, not a second more:
• No commitment
• Customisable
• Super simple
3D icon of a furnished living room, illustrating Lovys home insurance

Why is our landlord insurance so affordable?

Online insurance
Our 100% digital model lets us keep the price of our insurance down. We don't have to pay rent for branches, so you pay less!
Fully customisable
Choose only the options you really need, so your landlord insurance truly suits you.
Free cancellation
We cancel your old policy for you, free of charge! Cancelling your Lovys policy is also free and as easy as pie, even if it breaks our hearts every time.

The cover included in our landlord insurance

Damage
Fire, natural disasters, weather events, water damage and glass breakage are covered by landlord insurance.Storms, fire, water damage, glass breakage… It's all covered by second home insurance.
These different types of cover are included as standard in your policy. Whether it's a leaking washing machine, a storm dislodging roof tiles or a pigeon smashing a window, your property is protected.
Reimbursement of your costs
Whether it's rehousing costs after a claim or bringing the property up to standard during renovation work, you're protected.In the event of theft, attempted theft or vandalism at your second home, count on us to protect you.
If a damaged building has to be rebuilt or repaired, we also cover the experts and architects of your choice, as well as decontamination, demolition and clearance costs, plus the cost of temporary fencing and security.
Theft and vandalism
Your property is protected against proven theft or attempted theft, as well as acts of vandalism (unless it's a Banksy).Your neighbours will love you! You and your loved ones are covered for damage caused to third parties.
If someone tries to break into your home, or succeeds and burgles it, we cover your costs. The same goes for acts of vandalism.

Your property is let. It stays protected.

Lovys

Your cheat sheet on landlord insurance

If the words "home insurance" combined with "non-occupying owner" send a shiver down your spine (and rightly so), you're in the right place. Let us guide you through the depths of the insurance world, and you'll come out wiser.

Well, maybe not, but at least you'll understand everything about landlord insurance.
Woman standing in her bright living room, illustrating Lovys landlord insurance

Is landlord insurance compulsory?

What is landlord insurance?

The difference between MRH and PNO insurance

Let's start with the basics. There are several types of home insurance. We know, why keep it simple when you can make it complicated? Anyway, comprehensive home insurance (MRH for short, from the French "multirisque habitation") is different from landlord insurance (also known as PNO, for "propriétaire non-occupant").

While both protect the property itself, only MRH insurance covers what's inside it. For example, if your washing machine suddenly decides to go haywire and flood part of your home, landlord insurance will only cover damage to the structure (such as the walls), whereas MRH insurance can reimburse your washing machine, provided it was included in your policy.

Both protect your property but are designed for different profiles:

  • MRH insurance is taken out by tenants or owner-occupiers
  • Non-occupying owners, on the other hand, take out landlord insurance, even if they let their property

Compulsory or not, that is the question

Landlord home insurance isn't compulsory, unless your property is in a jointly owned building (copropriété).

To make things simpler, let's look at a few examples:

  • You've bought a house in the countryside and don't plan to live in it, so you're not required to insure it
  • You've invested in a flat and want to let it out. Since your property is in a jointly owned building (the block the flat is in), you must take out landlord insurance. This applies even if your tenant takes out their own comprehensive home insurance.
  • You own a house that you let out: you're not required to take out home insurance, but your tenants are

What is landlord insurance for?

Logically, now that you know this insurance isn't compulsory, you're wondering what it's for. Very good question, let us answer it.

  • Even when empty, a property can still get damaged. A storm sends the roof tiles flying, a pipe bursts and weakens the floor… All sorts of disaster scenarios that could cost you a pretty penny in repairs. Unless your property is insured.
  • If your tenants aren't insured, your landlord insurance takes over.
  • Construction defects and other latent defects aren't covered by your tenant's insurance, but they are covered by landlord insurance.

How much does landlord insurance cost?

Once again, a very good question, but a tricky one to answer. The price of landlord insurance depends on many factors. But the average cost of landlord insurance is estimated at between €70 and €200 a year, or an average of around €10 a month.

So how do you get a landlord insurance quote? Simply run a free simulation on our website. In just 30 seconds you'll get a quote that you can then customise.

Why take out landlord insurance?

Which landlord insurance should you choose?

Specific cover depending on your situation

Let's take a quick look at the cover usually included in your landlord insurance:

  • Fire
  • Water damage
  • Public liability
  • Theft and vandalism
  • Storms and natural disasters
  • Acts of terrorism
  • Technological disasters

On top of these, you can add options such as the following (non-exhaustive list):

  • Furnished lets
  • Glass breakage
  • Damage to your swimming pool and hot tub (lucky you)
  • Rent guarantee insurance
  • Furniture storage costs

What does the Loi Alur-Duflot (Alur-Duflot Act) change for non-occupying owners?

Since the Loi Alur (Alur Act) of 24 March 2014, if you're a non-occupying owner, you must take out (at the very least) public liability insurance for your rented property. As we explained above, this insurance is also required for all co-owners in a jointly owned building, whether or not they live there.

Public liability insurance covers damage your property might cause to your neighbours or any tenants.
Discover all our home insurance offers

Relaxed woman on her sofa with her phone, illustrating Lovys homeowner insurance
Homeowner insurance
Owner-occupier or landlord: your property protected in just a few clicks.
Couple sitting among moving boxes in a bright flat, illustrating Lovys rent guarantee insurance
Rent guarantee insurance
Your rental income secured, without any complicated paperwork.
Smiling adviser wearing a headset, illustrating Lovys customer support

Need help?

Our team is here to help.
Write to us
We reply in under 30 minutes on average, during opening hours.
chat icon
Talk to an expert
Real-time answers from a member of our team.
Client space
Manage your policies, report a claim, find your documents and much more.